Latest update November 10th, 2026 6:38 PM

Latest News
- 13-year-old girl missing after reportedly entering canter at Mahaicony
- Godfrey Smith offers to quit MV Barima CoI after U.S. visa revocation
- ‘Spy Chief could face attempted murder, firearm charges’ – Legal sources
- Bill seeking unlimited benefits for former presidents to be debated tomorrow
- Pentagon war chief Hegseth expected to face House impeachment vote this week
Effective communication is vital!
– Consultant reminds Internal Auditors
By Kiana Wilburg
Effective communication is as essential to internal auditors as it is to journalists. That said,

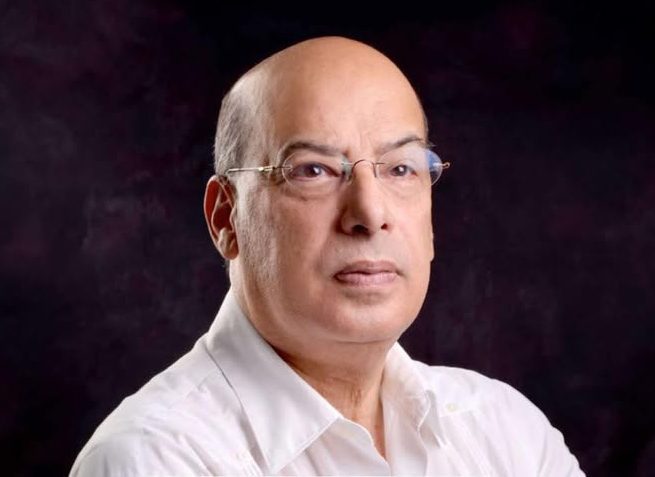
Mr. John Seeram, Financial Consultant and Governor of the (IIA) –Guyana Chapter
internal auditors cannot operate in a vacuum or even begin to perform their work effectively without gauging the responses of the organization they are attached to. Emphasis has to be placed on effective communication skills between the auditor and management.
Providing this perspective at a recent workshop was Mr. John Seeram, a financial consultant and Governor of the Institute of Internal Auditors (IIA) – Guyana Chapter. In his presentation to a number of internal auditors in Guyana, Seeram offered a few key tips which must be paid attention to.
COMMUNICATION CONSIDERATIONS
Seeram provided some of the major considerations the auditor has to keep in mind when determining how best to communicate audit observations. In this regard, he said, “Make sure the observations are correct; plan the timing of issue of dissemination; write in clear language; exercise diplomacy; understand the risks involved; make recommendations to add value to the organization; apply and uphold the institute’s code of ethics and make sure the observations are correct.”
While this seems obvious, Seeram explained that issues are not always validated before they are communicated to management. He said that having an audit examination challenged, and not being able to support its validity can harm or embarrass internal auditor’s ability to convince management to take action on legitimate issues, and they can significantly harm their reputation.
Seeram stressed that it is imperative that there is a high degree of accuracy of the observations being communicated.
TIMING OF DISSEMINATION
With regard to the timing of issue of dissemination, Seeram said that Management needs to know about observations as soon as possible, but not so early that the auditor cannot support the issues identified.
He said that this is a balancing act and there is the need to consider each manager’s potential actions when receiving information. He also said that there is the situation whereby some managers will immediately react, regardless of the significance of the issue, or their preparedness to resolve the issue, which may or may not make sense, depending on the nature of the issue.
Considering what the auditor knows about the client’s managers and their temperaments, Seeram articulated that he/she should present their issues appropriately at the right time.
He stressed that surprising management with all the issues at the end of an audit is damaging to the auditor-management relationship, and can have an effect on gaining management’s support for the auditor’s efforts.
CLEAR LANGUAGE
Seeram told participants that it is important not to soften an observation to the point that the reader does not realize the importance or value in it. He stressed to internal auditors that a report written in a strictly negative tone may also limit management’s engagement in the observations, and its desire to work with internal audit to resolve noted items.
He emphasized that there is more than one way to say something, and typically there is a way to say something to be accepted, and another way to be rejected.
“A lack of appropriate wording may result in management not seeing the value of the work of the auditor. Taking into consideration that the goal is to create action to mitigate risk and to resolve concerns, the specific words internal audit uses are indeed important.”
Seeram stressed that audit reports should be written in simple language and should, among others; address the root cause, for example a control deficiency; address the department rather than a person; include bullets or numbering when describing a process that has several steps; and position the most important observation or risk first, and the rest in descending order of risk .
EXERCISE DIPLOMACY
The Consultant explained that an internal audit department can improve its relationship with management even when communicating observations, by exercising diplomacy.
In this regard, he said that the auditor should take the opportunity to acknowledge management’s achievements and its efforts to mitigate risks, and to show management that internal audit’s role is not only to focus on the identification of issues.
UNDERSTANDING RISKS
Seeram explained that internal audit’s clients understand their operations. He said that they know what their departments do, and they have considered the risks related to their functions.
Seeram said that if the auditor cannot show that he/she understands the client’s operations, it may be hard for the auditor to communicate their observations in the way management is willing to listen to or can understand.
The presenter said that one of the quickest ways to lose management’s respect is for management to make it clear that internal audit does not understand what it has been auditing.
In order to avoid this, Seeram said that the answer is for the auditor, among others, to take the time to learn of the operations and risks associated with the area being audited.
MIXED REVIEWS
Some of the workshop’s participants felt that Seeram’s delivery was quite eloquent and informative. There were others however, who felt that it was purely academic and not as practical as it should have been.
Auditors in attendance also expressed the view that perhaps such training sessions should extend beyond those in the financial realm and include stakeholders who they have to interact with, so as to deepen their sense of appreciation and understanding regarding the work of an internal auditor.
Seeram said that while he took all the points expressed in good faith, he was faced with time constraints and crafted his presentation based on that factor.
ADDING VALUE
Seeram believes that one of the ways internal audit departments can add value to an organization is through recommendations communicated in its reports.
He noted, however, that recommendations also can become a point of contention with management, since they may suggest, as an example, additional procedures for staff, or can offend management if not presented correctly.
The Financial consultant said, “The auditor should take care to communicate with management, how the recommendations will help to fix gaps and mitigate risks. Management on the other hand will evaluate whether the recommendations being provided are worth the investment of time and resources required to implement them. This is costs versus benefits.”
Once the aforementioned points are used, Seeram said that there is no doubt that internal auditors would be able be successful in the pursuit of excellence.
Share this:

Discover more from Kaieteur News
Subscribe to get the latest posts sent to your email.
Similar Articles
Website Hits
Blunt of the day

Sports

Features/Columnists
Sir. Ronald Sanders
The GHK Lall Column

Weekend Cartoon