Latest update September 17th, 2026 10:25 AM

Justice Persaud’s ruling on post-clearance duties is sound in law
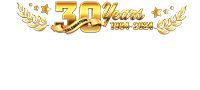
Kaieteur News – Much of the adverse public commentary surrounding the recent judgment delivered by Justice Gino Persaud in the matter involving businessman Azruddin Mohamed has been misplaced and, in some cases, downright misleading. The ruling is being caricatured as an “ouster” of the Guyana Revenue Authority’s power to recover customs duties after goods have been cleared. But that, in my humble opinion, is not what the Court held.
In my opinion, what the judgment does—and does correctly—is to implicitly affirm a long-standing and fundamental distinction between post-clearance tax recovery for customs duties and post-assessment recovery for income taxes. These are governed by two entirely different statutory regimes, with separate enforcement mechanisms, thresholds, and legal consequences. And the jurisprudence, both local and Commonwealth, supports the distinction.
For decades, the courts have recognised that taxes on income and taxes on imported goods operate under distinct statutory frameworks. The assessment regime under income tax statutes allows the Commissioner to make a best-judgment assessment, subject to objection and appeal, and that recovery can occur through civil proceedings regardless of intention or fault. The logic is simple: income tax is an annual, self-reported obligation, and the Commissioner’s power to reassess is the backbone of the system. Customs duties, by contrast, fall into the category of transactional taxes—taxes tied to a single event: importation. The applicable regime is primarily the Customs Act, which treats undervaluation and false declarations not merely as civil non-compliance but as criminal offences.
It is not novel or unusual for the courts to rule that post-clearance recovery of evaded duties depend on demonstrating the commission of an offence such as fraudulent concealment or under-declaration, and that customs recovery mechanisms hinge on whether statutory conditions—particularly those linked to declarations—have been satisfied. In other words: income tax recovery is civil; customs tax recovery is offence-driven unless expressly stated otherwise. Justice Persaud’s judgment simply respects this historical and statutory divide.
Criticisms of the recent judgment revolve around the idea that the judgment prevents the Guyana Revenue Authority (GRA) from reassessing duties. That is inaccurate. What the ruling implies is that there is no general authority for the GRA to simply decide—after clearance—that it now believes duties were underpaid, raise an arbitrary assessment, and file a civil claim. Customs law does not work that way.
Import duties are fixed at the point of entry, based on the declaration made and the goods examined. If the Authority later discovers that the declaration was false, or that the value was deliberately understated, that is not a civil issue—it is a criminal one. The GRA must invoke the mechanisms provided in the Act: charges for false declaration, under-valuation, or evasion. What the Judge held is implicitly straightforward: First, customs duties may be recovered post-clearance only by following the mechanism the law provides—criminal charges including for false declaration, improper classification, or evasion. The GRA may not bypass the statutory process by fabricating an arbitrary assessment.
The GRA did in fact charge the importer for alleged under-declaration of duties. That is the proper mechanism under the Customs Act. But those criminal charges were recently withdrawn by the Director of Public Prosecutions. The GRA therefore is fully aware of what it needs or needed to do to recover taxes. It needed to file criminal charges and prosecute them. Thus, if the GRA is aggrieved, its quarrel is not with Justice Persaud but with the DPP’s decision to withdraw the charges. The withdrawal of those charges had the legal effect of collapsing the only mechanism through which post-clearance recovery could occur. Far from granting immunity to importers, Justice Persaud’s judgment upholds the rule of law. It confirms that revenue cannot be recovered using powers that do not exist. And secondly that criminality must be proven before criminal-contingent remedies are invoked. This is not only correct; it is necessary in a constitutional democracy. The ends of taxation, however important, do not justify unlawful means. If Parliament believes the GRA should possess post-clearance civil reassessment powers, it is free to amend the Customs Act. Until then, the Court is right to prevent the Authority from exercising powers it does not have. That is not an ouster. That is the law.
(The views expressed in this article are those of the author and do not necessarily reflect the opinions of this newspaper.)
Share this:

Discover more from Kaieteur News
Subscribe to get the latest posts sent to your email.
- Azruddin Mohamed, Guyana Revenue Authority’s, Justice Persaud’s, legal consequences, mechanisms, thresholds
Similar Articles
Website Hits
Blunt of the day

Sports

Features/Columnists
Sir. Ronald Sanders
The GHK Lall Column

Weekend Cartoon