Latest update September 21st, 2026 10:57 AM

Latest News
- Defense accuses Police of misrepresenting court testimony, Magistrate says court unfazed by media
- Mohamed alleges political hand behind review of Justice Persaud’s U.S. visa
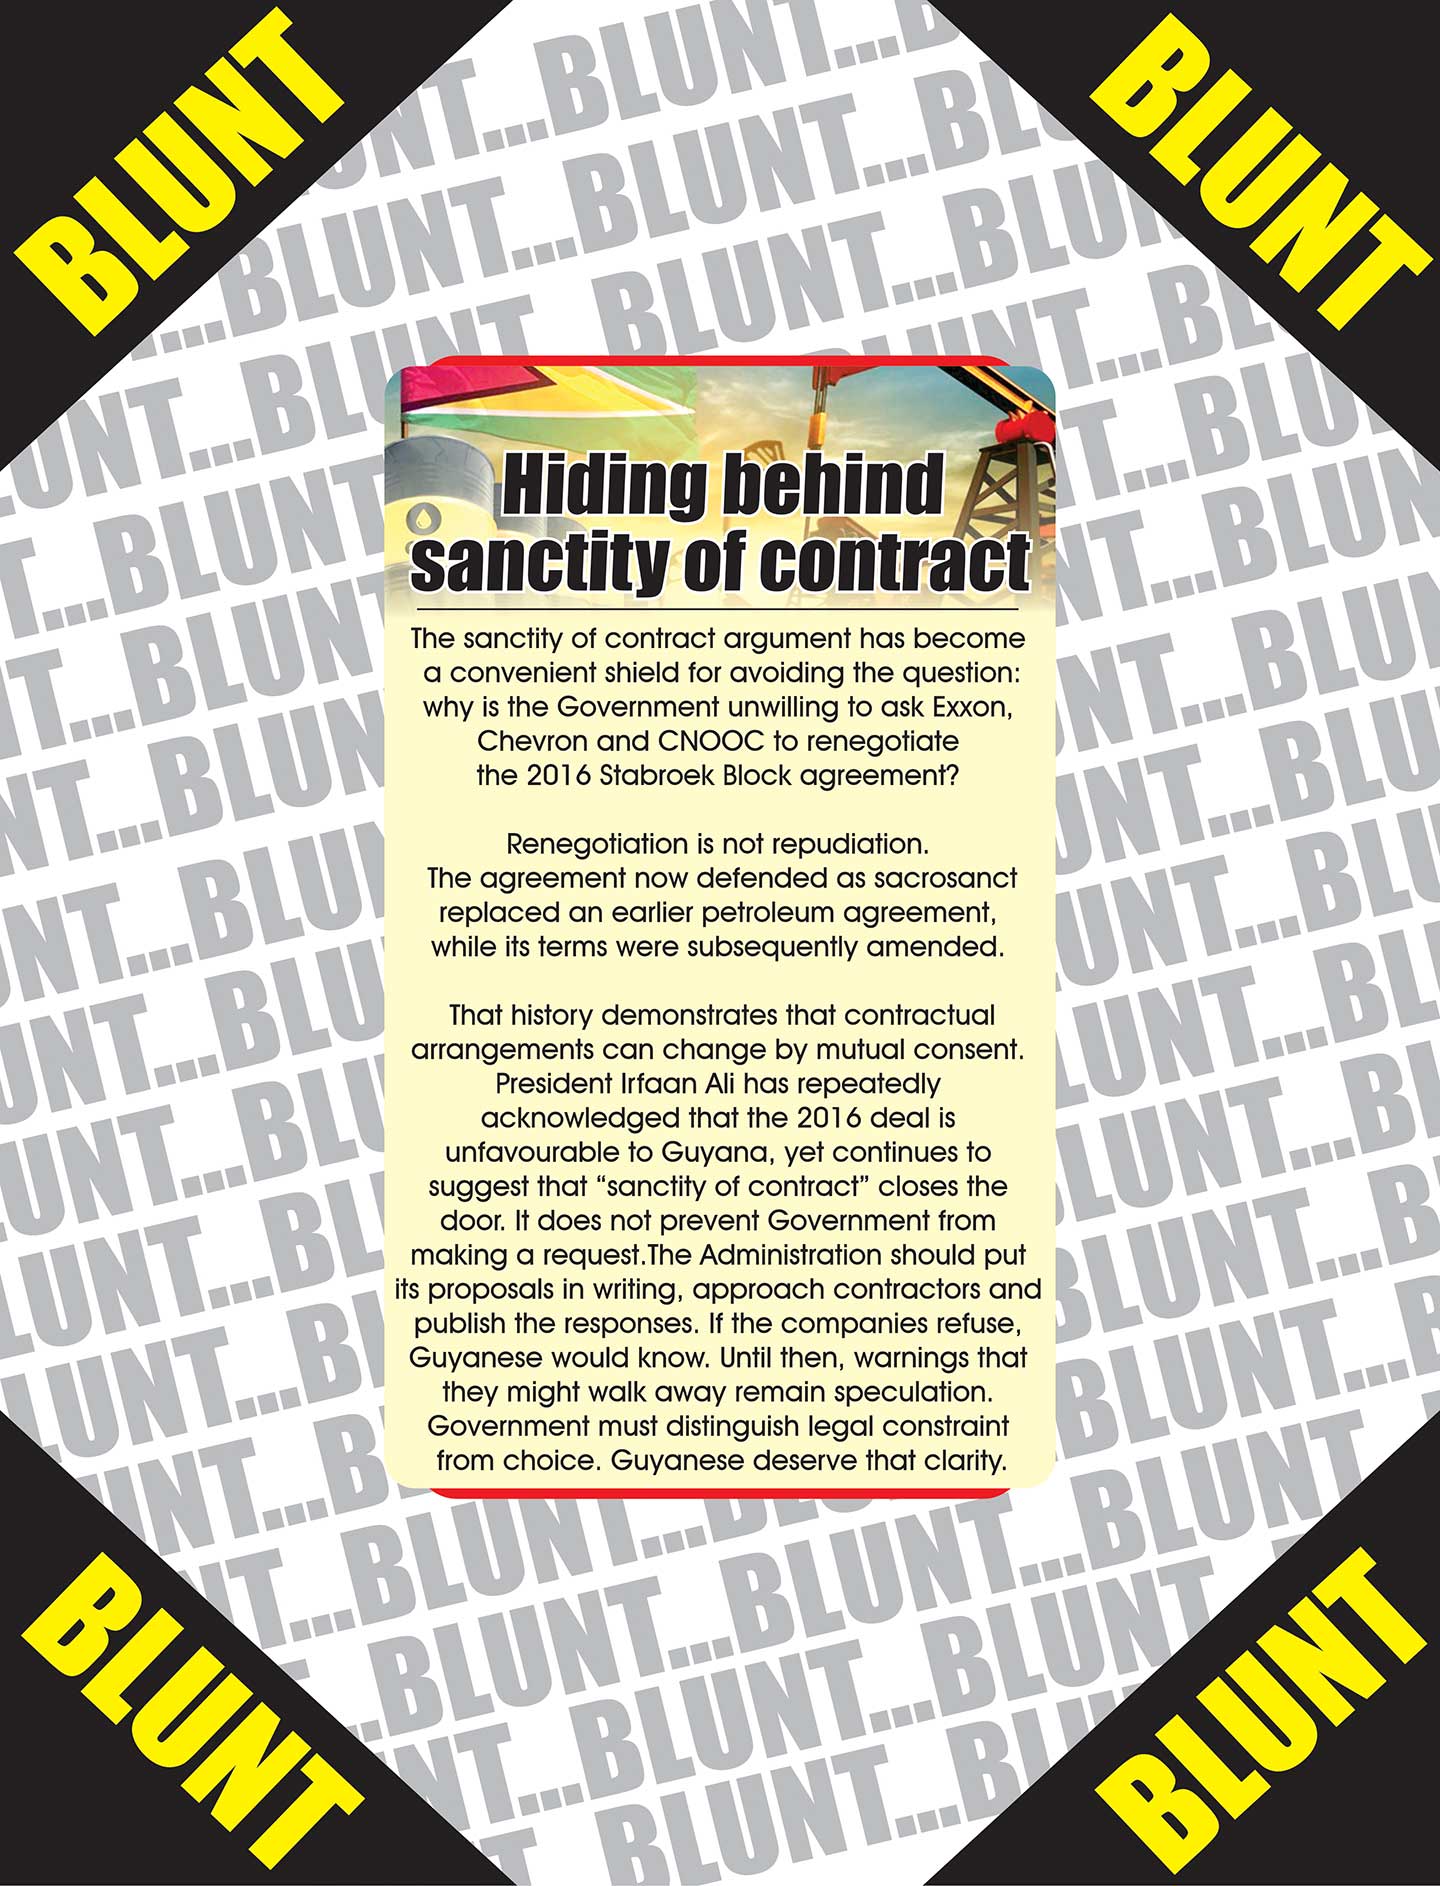
- ‘Stop blaming ‘sanctity of contract’ for keeping 2016 oil deal – Chris Ram tells Pres. Ali
- Iran and U.S. trade threats after Houthi attacks escalate regional conflict
- LIAT flight turns back to CJIA after engine issue
Borrowing on Oil
Editorial…
Kaieteur News – Guyana’s debt has crossed a historic and troubling threshold. With total public debt projected to surpass US$10.3 billion in 2026, many citizens are asking an uncomfortable but necessary question: how can a country swimming in oil revenues still be borrowing at such a furious pace?
The People’s Progressive Party (PPP) administration insists that the debt remains “strongly sustainable,” pointing to improved debt-to-GDP ratios and lower debt servicing as a percentage of government revenue. On paper, those indicators may appear reassuring. But beneath the numbers lies a risky development model increasingly dependent on borrowed money and volatile oil revenues to fund even routine national spending.
The 2026 national budget of $1.558 trillion is fueled by US$2.6 billion in new loans, on top of US$2.4 billion in oil revenues and nearly US$239 million in carbon credit earnings. This means borrowing now rivals oil as a primary funding pillar of the national budget. That should alarm every Guyanese.
Guyana’s public debt has ballooned at breathtaking speed. It stood at US$5.9 billion in 2024, jumped to US$7.7 billion in 2025, and is now projected to rise beyond US$10 billion this year. Such rapid accumulation is not the hallmark of fiscal restraint, but of a government spending aggressively today while deferring the true cost to tomorrow’s taxpayers.
What makes this approach particularly risky is the assumption that oil revenues will remain steady or grow indefinitely. Oil prices are notoriously volatile. Global demand shifts, geopolitical tensions, energy transitions and economic slowdowns can quickly slash prices. As opposition MP Dr. Terrence Campbell rightly cautioned, even a drop from the US$60 range into the US$50s per barrel would significantly reduce Guyana’s expected revenues. That scenario is not hypothetical, it has happened repeatedly in global markets.
Borrowing heavily while relying on unpredictable oil income is akin to building a house on shifting sand. When prices fall, debt obligations do not. Interest payments still come due. Infrastructure projects still require financing. Public sector wages still must be paid. The burden then shifts to citizens through higher taxes, reduced services, or austerity measures.
Equally concerning is what the borrowing is being used for. While some loans fund transformative infrastructure, roads, bridges, hospitals and energy projects, a troubling portion supports routine government operations. Borrowing to fund long-term productive assets can be justified. Borrowing to finance recurrent spending is a red flag.
The government often highlights that Guyana’s debt-to-GDP ratio has declined from 47.4 percent in 2020 to 28.6 percent in 2025. But GDP itself has exploded due to oil production. A growing economy does not automatically mean growing fiscal resilience, especially when that growth is tied to a single commodity sector. There is also the matter of foreign exposure. Bilateral and multilateral debt is increasing sharply, with loans from institutions and governments abroad climbing at a fast pace. External debt comes with currency risks. A weakening Guyana dollar or global financial tightening could make repayment more expensive and complicated.
Another danger lies in political culture. The trend of “largest budget ever” announcements has become a badge of honour. Bigger budgets are celebrated as proof of progress. But size alone does not equal sustainability. Responsible governance is not measured by how much money is spent, but by how wisely it is managed and how resilient the economy becomes when external shocks occur.
Guyana stands at a rare crossroads. Few countries have received such a sudden windfall from natural resources. This moment should be used to strengthen savings buffers, diversify the economy, reduce borrowing, and invest strategically — not to normalise debt expansion. Oil wealth should be a shield against excessive borrowing, not an excuse for it. If current trends continue, Guyana risks repeating the mistakes of many resource-rich nations: overspending during boom years, accumulating debt during good times, and scrambling for stability when prices fall. The government must slow the pace of borrowing, prioritise projects with clear economic returns, strengthen fiscal transparency and build stronger savings mechanisms. Citizens, too, must remain vigilant and demand accountability. Oil will not last forever. Debt, however, has a habit of staying long after the wells run dry.
Share this:

Discover more from Kaieteur News
Subscribe to get the latest posts sent to your email.
Similar Articles
Website Hits
Blunt of the day
Sports
Features/Columnists
Sir. Ronald Sanders
The GHK Lall Column
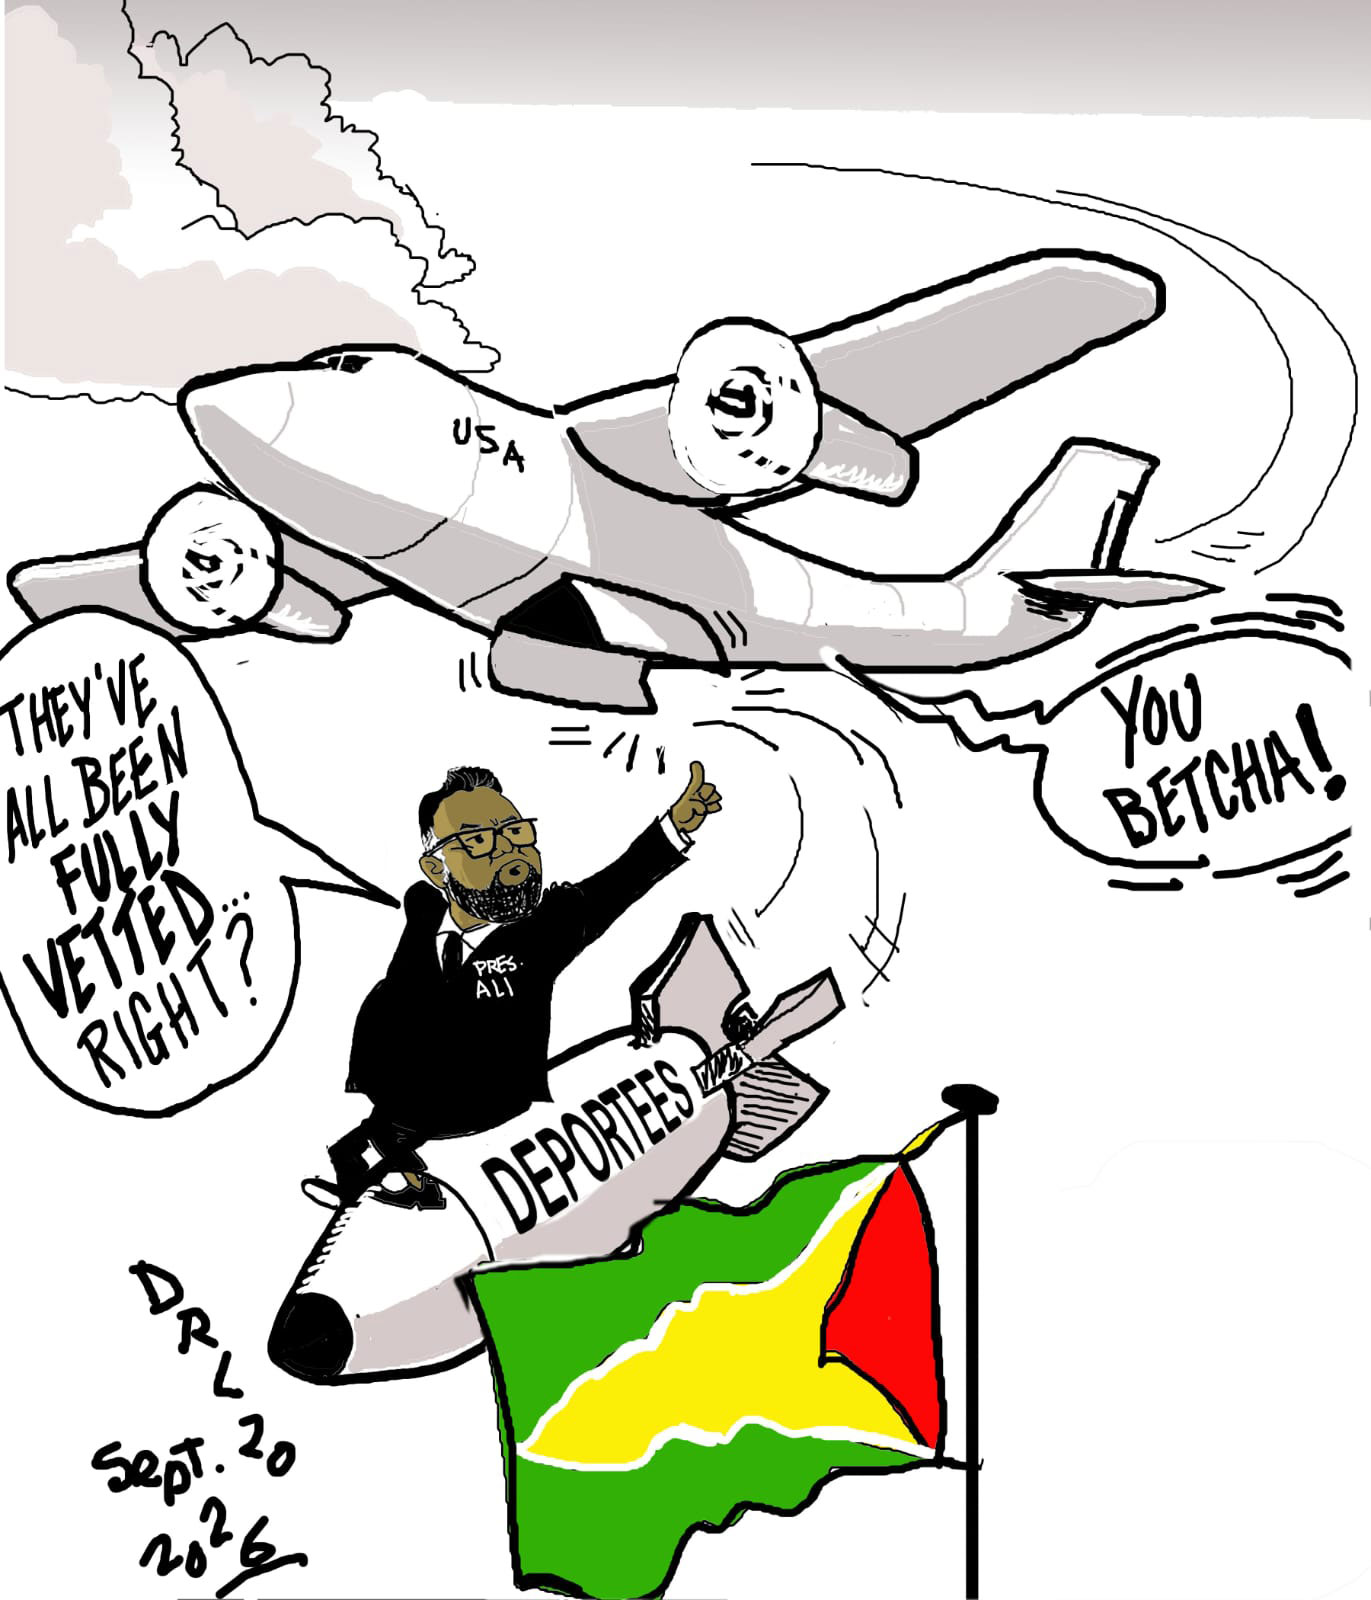
Weekend Cartoon