Latest update September 21st, 2026 2:51 PM

Latest News
- Three killed in Baramita clash
- Defense accuses Police of misrepresenting court testimony, Magistrate says court unfazed by media
- Mohamed alleges political hand behind review of Justice Persaud’s U.S. visa
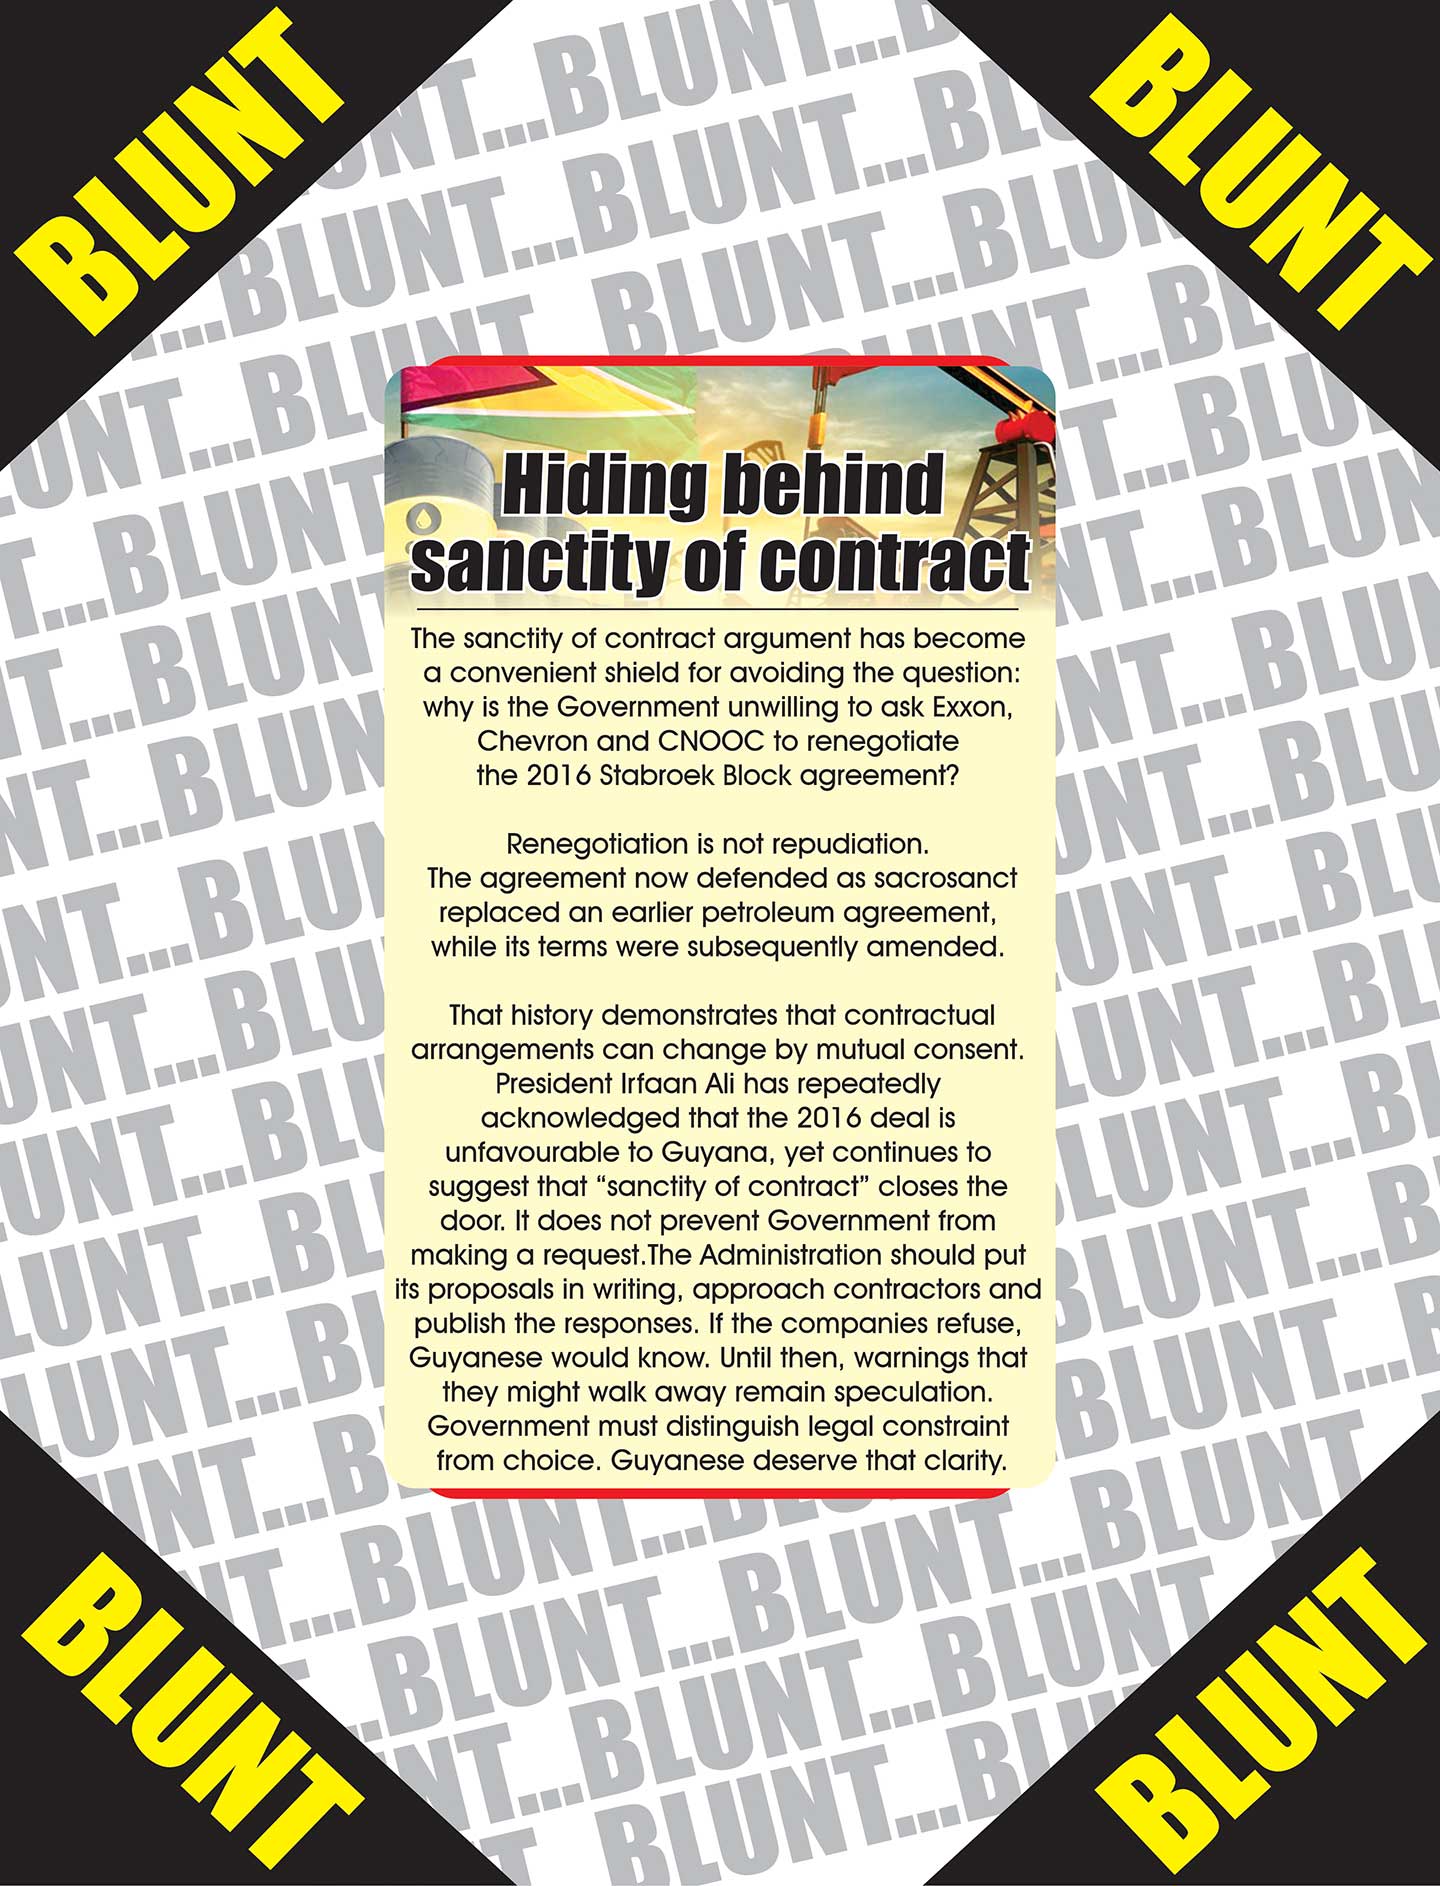
- ‘Stop blaming ‘sanctity of contract’ for keeping 2016 oil deal – Chris Ram tells Pres. Ali
- Iran and U.S. trade threats after Houthi attacks escalate regional conflict
The gift that keeps on accumulating
Kaieteur News – There are two kinds of parents in this world. The first kind, spend months debating the type of wrist band or bangle to have the goldsmith make, whether it should have embedded diamonds, whether it should be made of 14 or 18 carat gold and whether it should weigh half a pound and have the child’s name engraved on it.
The second kind quietly goes to the bank, opens a savings account for their newborn, and deposits ten thousand dollars. Guess which parent actually gives their kid something that might matter in twenty years? (Hint: it’s not the one whose bangle costs more than a used Toyota Fielder Wagon.)
Now, I understand the hesitation. Opening a savings account these days feels about as thrilling as watching a snail crawl across a wet sidewalk. Banks pay so little interest that your money would probably grow faster if you stuffed it under the couch cushions and wait for a coin to roll under there during Christmas cleaning. Parents look at those microscopic interest rates and think, “Why bother? I’ll just buy the kid a gold chain the size of a bicycle chain and call it an investment.”
But here’s the thing: jewellery is shiny, but it also comes with a built-in feature called disappearing. It gets stolen, lost, or traded in high school for a video game console. But a savings account, while not very sparkly, is safe, boring, and persistent. In fact, it’s supposed to be boring. That’s the whole point. Boring is what you want when it comes to protecting money, not excitement. Excitement is what you get from video games or politicians selling you on promises.
The real value of a savings account isn’t the interest rate; it’s the habit. When you open that account for your child, you’re teaching them the ancient art of setting something aside for later. Humans are not naturally good at this. If cavemen had discovered ice cream, we’d all be extinct, because they’d have eaten it immediately instead of saving some for winter. Saving is unnatural, like flossing or reading the terms and conditions. It has to be practiced.
That’s why starting early matters. Even if you’re only tossing a few thousand dollars into that account every month, you’re building muscle memory for your kid. They grow up knowing that money isn’t just for spending on shiny things, but also for preparing for that inevitable “rainy day”, the one where the phone gets dropped in the toilet, or when they need to make a downpayment on that vehicle or house they desire.
And let’s not forget compounding interest, which sounds like a boring math term but is actually the universe’s way of rewarding you for being patient. The idea is that your money earns a little interest, then that interest earns a little more interest, and eventually, after 30 years, you’ll have a balance large enough to buy a modest sofa. Okay, maybe not a mansion, but it adds up.
Older generations knew this. Remember when schools had little savings programs where kids would bring in coins to deposit? Or when workplaces had credit unions that encouraged thrift instead of pushing credit cards with 29% interest rates? Somewhere along the line, society decided saving was for chumps, and now we’re shocked when people can’t handle a $200 emergency. It’s because we traded “save now, spend later” for “spend now, panic later.”
So yes, buy the bangle or the wrist band. Yes, buy the teddy bear with Bluetooth. But if you really want to give your child a head start, open that savings account. Make it the first line in their biography: “Born on Tuesday. Given a bank account on Wednesday.” Then keep adding to it, little by little, like feeding a piggy bank on life support. The balance won’t look like much at first, but fast-forward a decade or two, and your kid might actually have something to cushion them through life’s bumps—or at least pay for extra lessons.
The bottom line is that life is unpredictable. Fun is fleeting. Jewellery can vanish. Toys break. But that boring, unglamorous savings account? That’s the gift that keeps on giving, or at least sitting there quietly, compounding in its dull little way. And one day, when your child withdraws money for house, a car, or to bail you out of your own retirement crisis, they’ll thank you. Maybe not with words. Maybe with a birthday card that actually has cash inside. But they’ll thank you.
So if you’re wondering what to give your newborn then skip the diamond earrings. Skip the overpriced stroller. March into that bank, open a savings account, and drop in the first deposit. It’s not flashy. It won’t go viral on Instagram. But one day, when your child has the cushion they need, you’ll look like the wisest parent alive.
And that’s better than any stroller or tricycle.
(The views expressed in this article are those of the author and do not necessarily reflect the opinions of this newspaper.)
Share this:

Discover more from Kaieteur News
Subscribe to get the latest posts sent to your email.
Similar Articles
Website Hits
Blunt of the day
Sports
Features/Columnists
Sir. Ronald Sanders
The GHK Lall Column
Weekend Cartoon